7 Strategies to Meet VA Loan Requirements for Manufactured Homes in Richmond, VA
This guide breaks down manufactured home VA loan requirements for veterans buying in the Richmond, VA area, covering HUD certification, real-property conversion, and foundation compliance. It outlines seven practical strategies to confirm eligibility upfront and avoid delays at appraisal or title.
How to Navigate the New Construction Home Loan Process in Richmond, VA (2026)
This guide walks Richmond, VA buyers through the new construction home loan process step by step, from getting pre-approved before meeting a builder to tracking draw schedules and converting to permanent financing at closing.
Student Loan Debt & Mortgage Qualification in Richmond, VA: 2026 Program-by-Program Guide
Student loan debt doesn’t have to block your path to homeownership in Richmond, VA — but which mortgage program you choose dramatically changes how that debt is counted against your DTI. This 2026 program-by-program guide breaks down exactly how VA, FHA, and Conventional loans handle student loan debt mortgage qualification so Richmond buyers can choose the approval path that works for their financial picture.
How to Use Rental Property Income to Qualify for a Mortgage in Richmond, VA (2026 Guide)
This 2026 guide explains exactly how underwriters use rental property income to qualify mortgage applicants in Richmond, VA, covering FHA, VA, and conventional loan rules — including vacancy factors, Schedule E calculations, and DTI impact — so Richmond investors can approach the approval process with realistic, lender-ready expectations.
Land and Construction Financing in Richmond, VA: 2026 Complete Guide
Land and construction financing in Richmond, VA combines land acquisition and a construction draw period into a single one-time-close loan — locking your permanent rate upfront and eliminating the cost and complexity of double closings. This 2026 guide walks Richmond buyers through every phase of the construction-to-permanent process, from raw land to finished, appraised home.
Refinance Application Documents Needed in Richmond, VA: 2026 Complete Checklist
Richmond, VA homeowners refinancing in 2026 need a precise, program-specific document stack to avoid delays — especially with loan amounts frequently approaching the $806,500 conforming limit. This complete checklist covers every Refinance Application Documents Needed category across VA IRRRL, FHA Streamline, and conventional rate-and-term refinances so Richmond borrowers can prepare a clean file and close on schedule.
Rising Interest Rates & Refinance Concerns: What Richmond, VA Homeowners Need to Know in 2026
Rising interest rates change refinance strategy, not the opportunity — and Richmond, VA homeowners in 2026 still have strong program-specific options including VA IRRRL, FHA Streamline, and cash-out refinance. Duane Buziak, NMLS #1110647, breaks down the mechanics, real dollar scenarios using Richmond median home price data, and a program comparison to help you decide your next move.
7 VA Loan Strategies for Rural Property Buyers in Richmond, VA (2026 Guide)
Richmond-area veterans have more flexibility than they realize when it comes to rural property VA loan options — VA financing can cover acreage, well and septic systems, outbuildings, and working land across Virginia. This guide breaks down seven actionable strategies to help veterans navigate the unique underwriting, appraisal, and lender overlay challenges that come with rural and semi-rural property purchases.
Why This Could Be Your Perfect Next Chapter
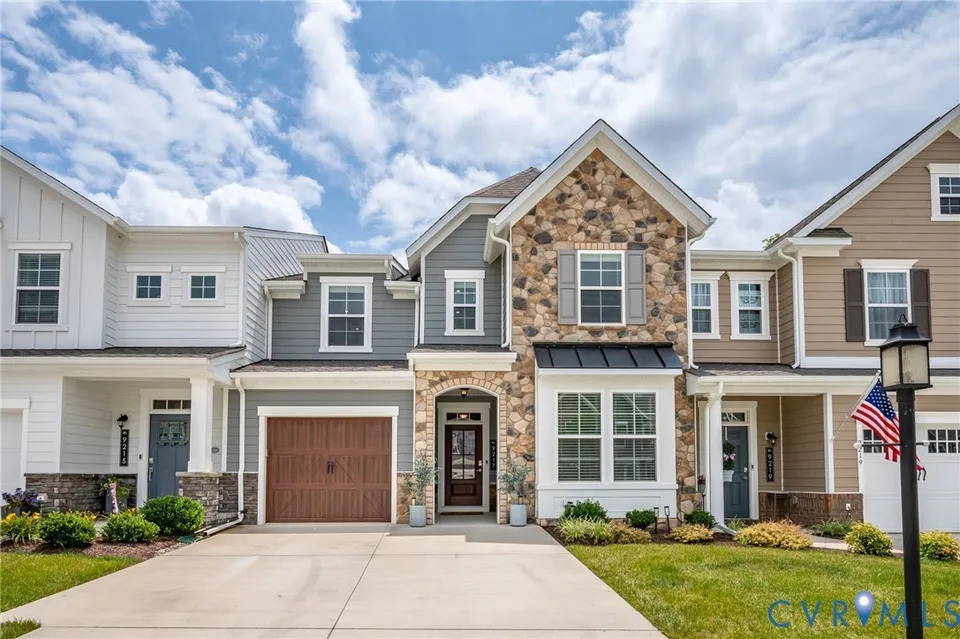
Finding the Right Home for the Next Stage of Life There’s a particular kind of home search that happens later in life — one that’s less about square footage and more about how a place makes you feel. It’s less about “what can we grow into” and more about “what will actually make our life […]
No Credit History? How to Get Your First Mortgage in Richmond, VA (2026 Step-by-Step Guide)
A no credit history first mortgage in Richmond, VA is achievable in 2026 through FHA, VA, and USDA programs that allow manual underwriting — meaning a human underwriter evaluates your real payment behavior, such as rent and utility records, instead of relying on a traditional FICO score. Duane Buziak, NMLS #1110647, breaks down each program path and the exact steps Richmond buyers with no credit file need to take to reach the closing table.